Demolition Contractor Insurance
Coverage for demolition operations, heavy equipment & jobsite liabilities.

Residential and commercial demolition contractors can face specialized insurance exposures involving structural collapse, falling debris, heavy equipment, dust, adjacent property, and hazardous materials. The right coverage depends on how the property, business, vehicle, or professional service is actually used.
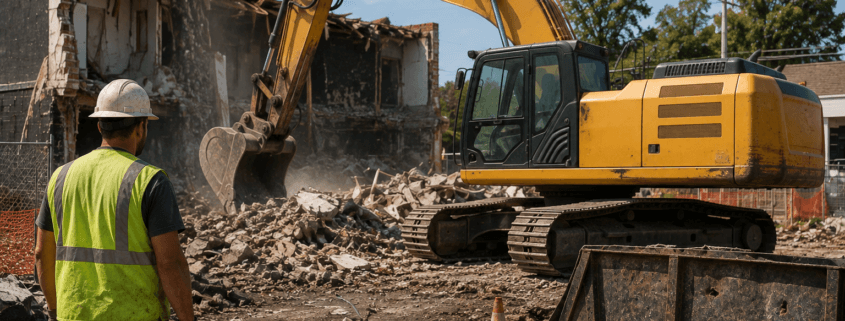 Coverage can be tailored to the individual situation. Select Risk Insurance Group can help clients in Louisiana compare available options from multiple insurance companies and review differences in coverage, limits, deductibles, and eligibility.
Demolition intentionally alters or removes structures, which creates unusually high property damage and bodily injury exposures. Project type, structural work, equipment, debris removal, and environmental hazards all affect underwriting.
Insurance can help transfer some of these financial risks, but no policy covers every situation. The appropriate combination of coverage depends on the specific details of the risk and the insurance companies willing to consider it.
The coverage that may be appropriate varies by client. Depending on the situation, an insurance program may include several different policies or endorsements.
General liability insurance may help protect against covered third-party bodily injury and property damage claims. It can be especially important when customers, vendors, or members of the public are exposed to your operations.
Commercial auto insurance may cover company-owned cars, vans, pickups, or trucks used for business. Coverage may include liability and physical damage options, depending on the vehicles and policy selected.
Workers’ compensation insurance may help pay eligible medical expenses and lost wages when an employee suffers a work-related injury or illness. Requirements and available options vary by state.
Tools, portable machinery, and equipment can be expensive to replace after theft or a covered loss. Inland marine or contractors’ equipment coverage may help protect property that regularly moves between jobsites.
Umbrella or excess liability insurance may provide additional limits above certain underlying liability policies when a covered claim exceeds those underlying limits.
Structural collapse, debris, heavy equipment, dust, neighboring property, underground utilities, and hazardous materials can create high-severity exposures.
General liability may help with certain covered property-damage claims, subject to exclusions and the circumstances of the loss.
Often it is worth considering because demolition can disturb asbestos, lead, fuel, mold, contaminated soil, and other pollutants excluded by standard liability.
Contractors’ equipment or inland marine coverage may protect eligible machinery against certain covered physical damage losses.